

JPay
3.9

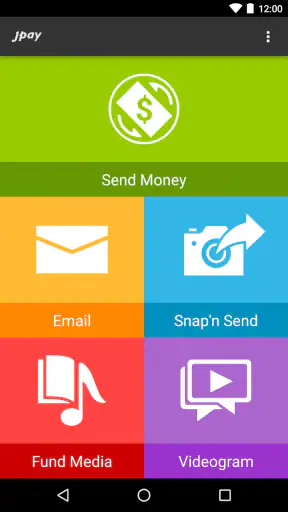
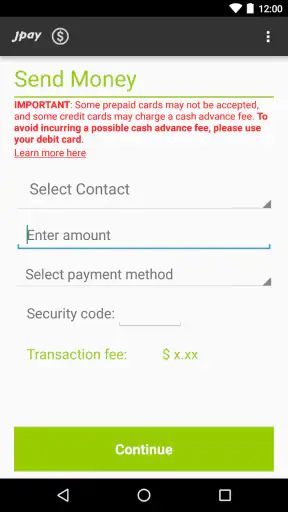
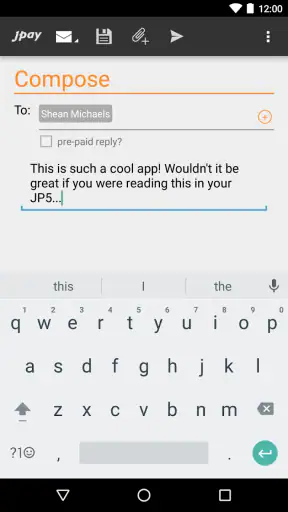
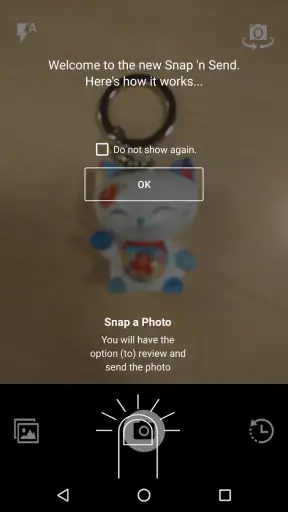
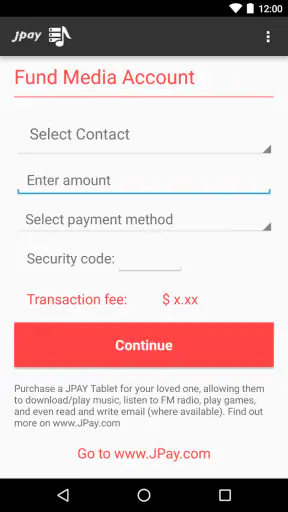
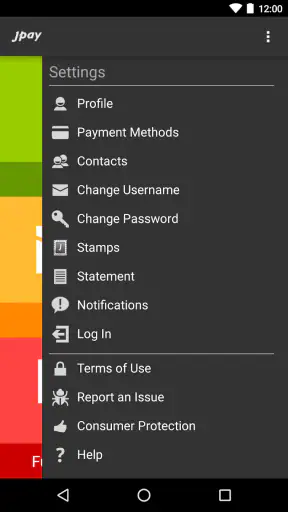
JPay is a finance app from Jpay Mobile that brings several tasks into one place for people who need to stay in contact with someone in a correctional facility. I found its purpose easy to understand: it lets you send money, exchange emails, share photos, and handle related communication from a phone instead of relying on several separate routines.
That focus makes it very different from a normal banking app or a general messaging service. It is not designed to replace your everyday bank, and it is not a social network for casual conversations. Its value comes from connecting financial support and communication in one specific situation. In my experience, that can remove a lot of searching and paperwork, but it also means the app is only a sensible choice for a particular group of users.
The app is free to install, carries a Teen content rating, and has been available since October 15, 2012. Its current version is 26.4.0 and it requires Android 11 or later. The scale of its audience is substantial, with over five million installs, while its average rating is 3.9 from roughly one hundred thousand ratings. Those figures suggest a service that many people depend on, but also one where individual experiences can vary depending on the facility, the account, and the transaction being attempted.
How I would use JPay from the first sign-in onward
I’d begin by checking that I have the right recipient and facility details before moving into any payment or message. From there, I’d make one small, low-pressure first session: confirm the account is ready, learn where each task lives, and avoid treating the app like instant chat. That gives me a clearer baseline for spotting whether a later snag comes from my setup or from the wider process.
Start by treating it as a service hub, not a regular wallet
The most useful way to approach JPay is to separate the things you want to do before tapping through the app. If I need to support someone financially, I first make sure I am working with the correct recipient and facility details. If I want to write, I prepare the message and any photo separately so I am not trying to compose everything while also checking payment information.
This sounds basic, but it is an important habit. A finance app can encourage quick actions, while communication naturally feels more personal and informal. JPay combines both areas, so rushing can lead to choosing the wrong function or overlooking a confirmation screen. I prefer to decide whether I am sending money, writing an email, attaching a photo, or doing several of those tasks before I begin.
For a realistic everyday example, imagine a family member needs money for approved personal expenses and you also want to send a short update. I would handle the financial transaction first, carefully review the recipient and amount, and then move to the email section. Keeping those actions mentally separate makes the process easier to check later and reduces the chance that an emotional message distracts me from a financial detail.
Keep communication and payments organized
JPay’s combination of messages, photos, and money transfers is its clearest strength. Instead of switching between a bank application, a separate email workflow, and another service for images, I can begin with one account and one app. That does not make every step effortless, but it gives the process a consistent starting point.
I would not use the message area as if it were an instant chat application. The service is better suited to deliberate updates: a family note, a question, a personal message, or a photo that has a clear reason for being shared. Writing in complete thoughts is especially helpful because the recipient may not be able to respond immediately in the way a normal messaging contact would.
For money transfers, I recommend slowing down at the final review stage. Check the recipient, the facility, and the amount every time, even when you have used the same details before. Familiarity is useful for speed, but it can also create careless habits. A saved or remembered destination should never be treated as proof that every current entry is correct.
What the app is good at for families
I see the strongest fit for relatives and close friends who need a repeatable way to maintain contact and provide financial support. The app can act as a single reference point for those responsibilities, which is valuable when several family members are involved and one person needs to keep track of what has already been sent or communicated.
It can also be useful for someone who is not comfortable managing multiple digital services. Rather than learning one app for transfers and another for correspondence, the user can focus on JPay’s narrower workflow. That simplicity is practical, although the app should not be mistaken for a general-purpose financial planning tool.
On the other hand, I would not recommend installing it merely because someone wants a normal mobile wallet, cheap peer-to-peer payments, or everyday banking. Its purpose is specialized. If your main needs are budgeting, bill payments, card management, or broad bank-account features, a conventional finance app will almost certainly be a better match.
Settings and account habits worth checking
Experienced use starts with account discipline. I would review the profile and recipient information before making a first payment, then keep personal contact details current. When an app is used for sensitive communication and financial support, an old email address or phone number can create more trouble than it would in a casual shopping app.
I also recommend checking notification behavior on your device. Notifications can be useful for reminding you to look at a message or confirm that an action needs attention, but they may reveal sensitive information on a lock screen. I prefer notifications that prompt me to open the app without exposing the full content of a personal message.
Another worthwhile habit is reviewing the phone’s general security settings. Use a screen lock, avoid leaving the account open on a shared device, and sign out when the phone belongs to someone else. These are not glamorous settings, but they matter more here because the app combines personal correspondence with financial activity.
Before sending a photo, I would also look at the image itself rather than attaching the first file that appears in the gallery. Check that it is the intended picture, that it does not include private information in the background, and that it is appropriate for the recipient and the service. A quick review before uploading is a simple way to avoid an uncomfortable mistake.
Build a repeatable routine for regular use
JPay becomes easier when the same sequence is used every time. My preferred pattern would be: open the app, confirm the intended recipient, handle the payment if one is needed, write the message, inspect any photo, and review the final details before submitting. Repeating that order reduces mental load without pretending that the app has shortcuts it does not advertise.
I would also keep a private record of important transactions and messages outside the app. That does not mean copying sensitive content everywhere. A simple note with the date, purpose, recipient, and amount can help a household coordinate support and avoid duplicate payments. It is particularly useful when several people share responsibility for helping the same person.
Use a calendar reminder if communication needs to happen regularly. The reminder should be for your own routine, not an assumption that a message or payment will be processed instantly. This distinction matters because the app connects you to a specific institutional environment, and the recipient’s access or response may not follow the rhythm of ordinary mobile messaging.
Faster patterns that still protect accuracy
Speed in JPay should come from preparation rather than tapping blindly. Before opening the app, have the message in mind, know which photo you want to send, and decide the amount if money is involved. This makes the session shorter while preserving the checks that matter.
For repeated correspondence, I would keep a small collection of personal prompts in a private note: family news, questions to ask, upcoming events, and practical updates. I would never reuse a message mechanically, but having topics ready prevents the familiar problem of opening a communication app and not knowing what to write.
When a payment and an email are both needed, completing one fully before starting the other is faster than moving back and forth. The app’s combined purpose is convenient, but multitasking inside one session can make errors harder to spot. A clean handoff between tasks is a better shortcut than trying to do everything at once.
Photos deserve their own repeatable check. Select the image, inspect the preview, confirm that it is suitable, and only then continue. This is a small workflow improvement, yet it is more useful than any imagined power-user trick because it directly addresses the risk of sending the wrong picture or including something unintended.
Where convenience meets friction
The main limitation is that JPay’s usefulness depends on a specialized communication and payment context. It is not a universal bridge between any two people. A user may find the app straightforward in one situation and less useful in another because the available experience is tied to the recipient and the relevant facility.
I also would not judge it by the standards of a modern social messenger. The important question is not whether it feels like a fast chat app, but whether it gives you a workable way to send the types of support and communication it is intended to handle. People expecting instant conversation, broad media sharing, or ordinary banking tools may feel constrained.
The rating of 3.9 reflects that mixed picture. It is high enough to show that many users find the service valuable, but it is not a signal that every interaction will be smooth. Finance-related actions naturally deserve more caution than a simple message, and the app’s specialized role means that frustration may come from the wider process as much as from the interface itself.
Limits advanced users should understand
There is a difference between becoming efficient and assuming control over parts of the process that belong to the institution or recipient. JPay can give you a convenient place to initiate communication and support, but it cannot turn that relationship into a normal unrestricted messaging channel. I would keep expectations realistic about timing, access, and the way a message or photo reaches its destination.
That is also why I would avoid sending urgent information through the app unless I already understand how the recipient normally receives and responds to messages. For time-sensitive matters, use the appropriate official contact route instead of assuming that an in-app action works like an immediate phone call.
Financially, the app should be treated as a transaction tool rather than a budgeting system. I would decide the household’s support budget elsewhere, then use JPay to carry out the specific action. This separation is one of the more important advanced habits: planning and record-keeping happen outside the transfer screen, while JPay handles the communication and payment workflow.
Privacy is another boundary. Because the app brings together personal notes, photos, and money-related activity, sharing account access casually is a poor idea. If more than one family member needs information, I would agree on a secure record-keeping method instead of passing around login details. Convenience should not come at the cost of losing control of the account.
Who should choose it, and who should skip it
I would choose JPay if I needed a focused way to stay in touch with a person in a correctional facility while also sending financial support through the same service. The ability to combine emails, photos, and money-related tasks is meaningful for that audience, especially when repeated contact is part of family life.
I would skip it if I only needed ordinary transfers to friends, a bank account overview, spending categories, or a standard chat service. A regular banking app is better for personal finances, and a mainstream messenger is better for immediate conversations with people who can use it normally. Installing JPay for those purposes would create unnecessary friction.
I would also think carefully before recommending it to someone who dislikes digital account management. The app may simplify the number of services involved, but the user still needs to verify recipient details, protect the account, review transactions, and understand that communication may not behave like instant messaging. A patient, careful user will get more from it than someone looking for one-tap convenience.
My verdict after using its workflow
JPay works best when you treat it as a focused bridge between financial support and personal communication. I like that it gathers meaningful tasks in one place, and I can see why families would prefer a dedicated service over juggling unrelated apps. The free installation also lowers the barrier to trying it, although the practical cost and transaction details should always be considered within the specific action you are taking.
My recommendation is positive but narrow. For the people it serves, the app can become a dependable part of a weekly or monthly routine. The best results come from a careful sequence: verify the recipient, separate payment from writing, inspect photos before sending, protect notifications and account access, and keep a private record of important support.
For everyone else, there are better alternatives. JPay is not trying to be a full bank, a budgeting dashboard, or a universal messenger, and judging it as one would be unfair. Its value is more practical than flashy: it gives a specific kind of user one organized place to maintain contact and provide support. If that is your situation, I think it is worth considering. If it is not, choosing a conventional finance or messaging app will likely make everyday tasks easier.
Jpay Mobile has kept the app available across many years, and the current Android release supports devices running Android 11 or newer. I would install it only after confirming that my phone meets that requirement and after deciding exactly which parts of the workflow I need. Used with realistic expectations and a consistent routine, JPay is a useful specialist app rather than an all-purpose financial solution.
3.9
36.05K Reviews
Pros
- Conveniently send money and emails to incarcerated loved ones.
- Supports photo attachments and electronic greeting cards.
- Transaction receipts help track payments and deliveries.
- Available on both Android and iOS devices.
- Useful for checking facility-specific services in one place.
Cons
- Availability and features vary significantly by correctional facility.
- Money transfers may include service fees and processing delays.
- Messages can be reviewed or delayed by facility staff.
- Some users report occasional login and app performance issues.
- Recipients may need approved tablets or kiosks to access content.


